The Growth Benchmark Blog
A private equity playbook for growth diligence: 5 steps before you sign.
by Russ Holder
Founder & CEO
RevGrowth OS, LLC
Every PE diligence process includes a growth workstream. Few have a growth diligence instrument that measures the target's growth infrastructure with the same rigor as a quality-of-earnings review. Here is a five-step playbook to close that gap before you own the company.
Quality of earnings tells you if the numbers are real. It doesn't tell you whether the mechanism that produced them will keep working under new ownership. These are separate questions. Treating the second as answered by the first is where many post-close growth surprises begin.
A target can pass QoE cleanly. The revenue and margin are real, with no adjustments hiding a problem. Yet growth may still depend almost entirely on a few people, a handful of relationships, and knowledge that exists only in someone's head. None of this shows in a financial statement. It becomes visible in year two, when the deal's excitement fades, and the people who drove the numbers start reassessing their options.
Growth diligence must run as its own workstream, with its own instrument. Legal, tax, and IT diligence each have dedicated processes. Growth should be no different. Here is what that looks like in practice.
This is why quartile position and upside potential move together. A top-quartile company is already close to the standard. Most of its 25 Drivers are tuned, and the gains left on the table are marginal. A bottom-quartile company has multiple Drivers running well below standard. Each one is a lever nobody has pulled yet.
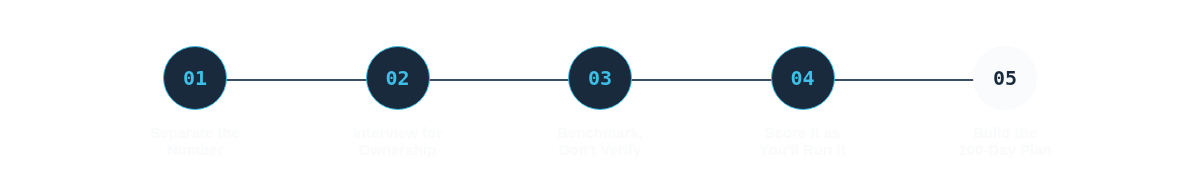
Step 1: separate the growth number from the growth system.
Treat the historical CAGR and the growth mechanism as two separate diligence questions. They are often collapsed into one, but they are not the same.
The CAGR answers one question: did this company grow? A separate inquiry must answer what produced that growth, and whether it is repeatable.
Break growth down by the individual driver. How much came from new logos versus existing accounts? How much from price versus volume? How much from a few large deals versus a broad base? A growth rate built on three outsized wins from three relationships is not the same as growth from a repeatable process across forty accounts, even if both show up the same on the top line.
This step alone often reveals whether you are looking at a system or just a run of good years.
Step 2: find out who's actually driving it.
Ask the heroics question directly in management interviews. Do not limit it to the CEO. If the top one or two revenue-producing people left the week after close, how much of this growth rate would remain?
Get specific. Who owns pricing decisions? Is that logic documented, or does it live in one person's judgment? Who owns the largest accounts? What happens to those relationships if that person exits during the transition? This is often when key people leave. How much of the pipeline came from the founder's personal network versus a repeatable channel that will still generate leads in eighteen months?
Management teams rarely volunteer this information. It is not usually deception. Most leadership teams have never been asked to separate being good at something from having a system for it. They often don’t know which is true until someone asks directly. Getting this answer requires structured interviews designed to surface it, not general management conversations.
Step 3: benchmark, don't just verify.
Verification asks if the target's numbers are accurate. Benchmarking asks how the target's growth infrastructure compares to similar companies. Most diligence processes skip this step because they lack the right instrument.
Score the target against the categories that determine whether growth compounds. These include strategic position, competitive advantage, the mix of acquisition, retention, and transaction that produces revenue, organizational resilience, agility under pressure, and how efficiently growth converts into enterprise value. Compare the result to a peer set of similarly sized companies, not just to the deal thesis's assumptions. A target can look strong relative to its own history and still be in the bottom half of its peer group. That changes what the 100-day plan should prioritize.
In the RevGrowth Benchmark's dataset of over 200 companies, the spread between top- and bottom-quartile companies on this scoring is about seven times the annual growth rate. This gap is real, measurable, and large enough to change a deal's underwriting.
Step 4: score it the way you'll run it.
This step is easy to skip and expensive to miss. The instrument you use in diligence should be the same one you use to run the business after close.
Diligence teams often build a one-off growth assessment for the deal, generate findings, and then hand the target to an operating team that has never seen that assessment. There is no way to re-measure against it later. Six months in, nobody can say whether growth infrastructure improved, because the yardstick from diligence and the yardstick from operations are not the same.
Score the target on the instrument you intend to keep using. Your value-creation team, portfolio operations group, or operating partners should re-run it at regular intervals. At a minimum, every year. Depending on the situation and the company, sometimes every 90 or 180 days is appropriate. This turns the diligence scorecard into a baseline, not a one-time exhibit in a deal deck.
Step 5: build the 100-day plan on a baseline, not a guess.
Most 100-day growth plans are built from the deal thesis, the CIM, and a few management interviews. These are informed guesses, made under time pressure before anyone owns the business.
A 100-day plan built on a real baseline is different. It starts with the specific Drivers the diligence benchmark scored as weakest, ranked by financial impact. The plan is sequenced against those Drivers, not just whichever initiative got the most attention in the management presentation. It also gives the new board a number to hold the operating team to, not just 'grow the top line.' It sets a specific quartile movement on a specific set of Drivers, measured the same way at the next re-benchmark.
This is where the earlier heroics finding pays off directly. If Step 2 found that growth depends heavily on one or two people, the 100-day plan needs a specific initiative to convert that knowledge into something documented and repeatable. Do this before those people's retention becomes uncertain.
The playbook in one page.
Five steps, in order.
- Separate the growth number from the growth system.
- Interview specifically for who is actually driving it, not just whether growth happened.
- Benchmark the target against real peers, not just the deal thesis's assumptions.
- Use the same instrument in diligence that you will use to run the company afterward.
- Build the 100-day plan against a measured baseline, not a guess.
None of this replaces quality of earnings, legal diligence, or the rest of a standard process. It sits alongside them. It closes the gap almost none of them cover: whether the growth number you are underwriting is an asset that will still be producing in eighteen months, or a number a specific person produced right up until the day you bought it.
The RevGrowth Benchmark can run this exact scoring on a target before you own it — the same 4 non-negotiables, 7 critical factors, and 25 Drivers used across 204 mid-market companies, applied to the deal in front of you. If you'd rather see it applied to your own numbers first, the RevGrowth Simulation is a free, one-hour place to start.
Benchmark your strategy. Engineer your growth.
When you’re ready to see where you actually stand, the RevGrowth Simulation is where this starts. One hour, your own numbers, no cost, and no proposal at the end of it.
The RevGrowth Score
Ten minutes to find out where you actually sit.
The findings tell you what the data says. They don't tell you where you are in it. The RevGrowth Score scores your company against some of the same non-negotiables and critical factors we score every benchmarked company on. Ten minutes, online, no call required.
You get a position, not a grade.
Ten minutes. Online. No call required.
The RevGrowth Simulation
Find out which one you are.
The RevGrowth Simulation is a one-hour working session using your own numbers. You'll see where your growth system sits against 200+ mid-market companies, and what the gap is worth.
60 minutes - built on your data - CEO level - no obligation